All Categories
Featured

One of the most attractive functions is the capability to access the cash worth through policy loans and withdrawals, typically on a tax-free basis, offered the policy is structured properly and remains in force. Policy loans are usually not thought about taxable income. Withdrawals approximately the quantity of premiums paid (your cost basis) are normally tax-free.
Insurance in Brea CANevertheless, it's essential to understand that if the policy lapses or is surrendered, outstanding loans and gains might become taxable. The adjustable premium payments and possible death advantage options supply a degree of flexibility not always found in other irreversible life insurance items. While focusing on cash growth, the policy still supplies a crucial survivor benefit for recipients, using financial defense for your loved ones.
The "finest IUL policies for money accumulation" will typically include competitive caps, involvement rates, and workable internal costs. The "finest business for IUL" for retirement planning might likewise provide beneficial loan provisions. Remember, these features need to be assessed together. A high cap may be balanced out by high charges or a low participation rate.
Because today's cap is not the entire story, our comparison of IUL renewal cap rates: F&G vs Pacific Life and Lincoln looks at how caps have altered over time. While IUL offers engaging potential benefits, it's necessary to approach it with a clear understanding of the associated dangers and costs.
Low-Cost Family Health Quotes
A reliable and credible method means acknowledging these aspects upfront. IUL policies are inherently more intricate than term life and even traditional entire life. Policy illustrations, which project future cash worth growth, are based upon various presumptions about index efficiency, crediting rates, policy expenses, and loan use. These are * projections *, not assurances.
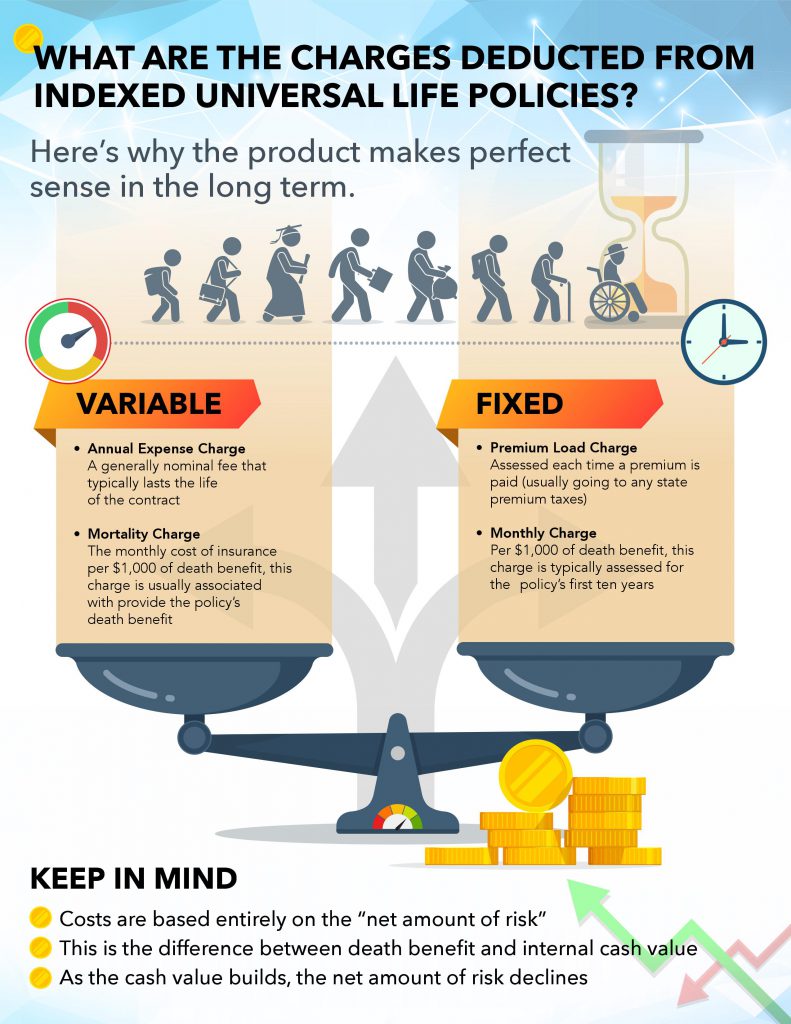
IUL policies have numerous internal charges that reduce money worth growth. These can consist of: The charge for the pure death benefit security.
Expenses for any additional advantages added to the policy. Costs used if you surrender the policy or withdraw considerable amounts, typically within the very first 10-15 years.
While the floor protects versus direct market * losses *, it does not guarantee favorable returns. If the linked index performs inadequately or stays flat for prolonged durations, your cash value may just make the floor rate (frequently 0%). After policy expenses are deducted, the money worth could potentially decrease in such years.
Even in flourishing market years, your credited interest won't exceed the cap. Involvement rates listed below 100% more minimize the credited interest relative to the index gain. Providers can sometimes adjust non-guaranteed aspects like caps and participation rates over the life of the policy (within contractual limits), which might impact long-lasting performance.

Latest Posts

Individual Health Insurance Quotes for 2026

Direct Consumer Advice for Life Insurance Selection
Life Insurance Options for Seniors in the USA